LADY LARISA
SANLORENZO SX88 Built by Sanlorenzo in 2018, LADY LARISA combines contemporary Italian design with versatile living spaces and a seamless connection to the water. Exterior
THE EYB COUNTRY GUIDES · Italy
Understand permanent import, private temporary admission, arrival evidence and the VAT calculation before moving a boat to Italy.
By Peter Mattey · 9 min read · Facts checked 2026-10-03
Importing a boat Italy questions begin with the customs route, rather than the flag alone. A purchase intended to remain in the European Union needs a different assessment from a qualifying private visit followed by departure. The ownership, user and travel history help establish which case you are dealing with. Before delivery, ask a customs representative to confirm the procedure and the evidence needed, then build the purchase timetable around that answer.
This guide covers permanent import principles and the Italian customs authority's current guidance for private temporary admission. It explains arrival records, the VAT calculation and repair pitfalls. It does not establish a tariff classification or special relief for a particular yacht. Obtain transaction-specific advice before committing to an import arrangement. For anything this guide does not cover, email us at info@europeanyachtbrokers.com for the latest information.
Key facts at a glance
Regulation (EU) No 952/2013 establishing the Union Customs Code, Article 201, subjects non-Union goods intended for the Union market or private use to release for free circulation, including applicable import duties, other charges and formalities.
EUR-Lex – Union Customs Code, updated 12 Dec 2022 ·ADM Circular 11/2026 explains Delegated Regulation (EU) 2015/2446, Article 212(3): the transport must be registered outside the Union in the name of a person established outside it, or if unregistered owned by such a person, and used by a person established outside it.
ADM – temporary admission Circular 11/2026, updated 15 May 2026 ·ADM Circular 11/2026 states that the maximum private-yacht temporary-admission period is 18 months from entry into the Union under Delegated Regulation (EU) 2015/2446, Article 217.
ADM – temporary admission Circular 11/2026, updated 15 May 2026 ·Presidential Decree 26 October 1972, No 633, Istituzione e disciplina dell'imposta sul valore aggiunto, Article 69, calculates import VAT on the customs value plus applicable customs charges other than VAT and forwarding costs to the Union destination shown in the transport document.
Normattiva – import VAT calculation, updated 14 Mar 1997 ·ADM Circular 11/2026 treats departure from Union territorial waters as discharge of private temporary admission and identifies Automatic Identification System data, third-country arrival documents, foreign bunkering records or logbook entries as possible evidence.
ADM – temporary admission Circular 11/2026, updated 15 May 2026 ·Section 1
Start by describing what you intend to do with the boat after arrival. Keeping a purchased yacht in the European Union is a different customs question from bringing a qualifying private yacht in for a visit and taking it out again. Ask a customs representative to identify the proposed procedure before arranging delivery. Provide the ownership details, registration, where the owner and user are established, and the intended use. These are recommended preparation steps, rather than a universal document checklist.
Release for free circulation is the customs route described in the Union Customs Code for non-Union goods intended for the Union market or private use. Temporary admission concerns non-Union goods intended for re-export and used under specified conditions. Do not read a foreign registration certificate as proof that the temporary route applies. The Italian customs circular also addresses the person in whose name the yacht is registered and the person using it. Establish those facts before relying on simplified arrival arrangements.
Temporary entry also needs to fit the activity you actually plan. A private owner's visit and a paid charter are different cases in the customs guidance. This guide addresses private use and does not transplant the private timetable into a commercial contract. If ownership, use or establishment changes during a proposed sale, obtain transaction-specific advice before signing. A locally qualified adviser can explain how the change affects the existing procedure and what must happen before the buyer takes control.
Broker tip: As a practical preparation step, send your adviser the proposed purchase and delivery arrangements together. Ask for a written explanation of the customs route before accepting a seller's description of the boat as already cleared. A related question is answered in our guide on whether you pay VAT on a boat in Italy.

Port customs office at a harbour.
Permanent or temporary
Section 2
Prepare the customs file before departure, rather than trying to reconstruct it at the first inspection. For a declared procedure, the Union Customs Code addresses both the declaration and the supporting documents available when it is lodged. Ask the representative handling your case to identify the documents needed for that procedure. As a practical recommendation, check that the owner's identity, boat identification and transaction details agree across the material supplied. Resolve discrepancies before a declaration is submitted on your behalf.
For qualifying private temporary arrivals, the latest Italian circular explains the simplified act of crossing the customs boundary. It also describes an optional verbal declaration and an alternative arrival attestation from the harbour authority. Those routes provide useful arrival evidence; they do not remove the substantive conditions for the procedure. Ask the relevant customs office which evidence it wants for your circumstances. Keep the response with the yacht's records so a later buyer or adviser can follow the history.
The arrival date matters across the Union, rather than only at your chosen Italian marina. A yacht that reaches Italy after visiting another member state needs a coherent account of that earlier entry. The circular places the evidential burden on the procedure holder where the simplified arrival method is used. Keep the available movement records together and make their chronology understandable. This is a recommendation for managing evidence, not a claim that a particular marina receipt is conclusive in every case.
Broker tip: Keep an accessible copy of the customs file as a practical safeguard. Give your representative the complete travel history, including earlier Union arrivals, so the advice does not begin with the wrong entry date. See also our guide on how to register a boat in Italy.
Passport and boat registration papers on a chart.
Documents and arrival
Planning to bring a boat into Italy and want to check the route first? Speak to one of our brokers.
Section 3
Do not build a permanent-import budget by applying VAT to the advertised boat price alone. The Italian import rule describes a taxable base that starts with the customs value and includes specified additions. Ask the customs representative to show the valuation, applicable customs charges and relevant forwarding costs separately. Then ask the adviser to explain which VAT treatment applies to your particular import. The ordinary rate is verified here, but the guide does not establish a special exemption for your yacht.
A useful written calculation separates verified tax rules from amounts that still need quotations or a customs assessment. For illustration only, assume the customs value, customs charges and forwarding amounts shown in the sourced facts below. The resulting arithmetic demonstrates how additions to the base affect VAT; it is not a tariff quotation or an import-duty rate. Before agreeing the purchase budget, replace every assumed input with the amount accepted for your actual transaction and identify who will pay each item.
A qualifying private temporary visit has a different time question from a permanent import. The Italian circular counts the private admission period from entry into the Union. Moving between member states does not change that starting point into an Italian arrival date. Prepare a movement chronology and ask the customs representative to assess the remaining period before buying or moving the yacht. No standard clearance processing time, agency charge or permanent-import duty percentage has been verified for all boats in this guide. Import duty rates, tariff classification, customs agent fees, clearance times, charter admission and relief for returning goods or residence transfers are not covered here: email us at info@europeanyachtbrokers.com for the latest information.
Broker tip: Request a calculation showing the customs value, additions, VAT treatment and payer as separate entries. Treat an illustrative calculation as a planning aid until a customs representative has confirmed the actual inputs for your boat. Readers often go on to our guide on whether you need a boat licence in Italy.

Model yacht beside a calculator for boat tax costs.
Import VAT and time limits
Presidential Decree 26 October 1972, No 633, Istituzione e disciplina dell'imposta sul valore aggiunto, Article 69, calculates import VAT on the customs value plus applicable customs charges other than VAT and forwarding costs to the Union destination shown in the transport document.
Source: Normattiva – import VAT calculation, updated 14 Mar 1997Presidential Decree 633/1972, Article 16, sets the ordinary VAT rate at 22% of the taxable base.
Source: Normattiva – VAT rates, updated 1 Jan 2016An explicitly assumed customs value of €200,000, customs charges of €4,500 and relevant forwarding costs of €1,500 gives a €206,000 VAT base; applying the separately sourced ordinary 22% rate gives €45,320 VAT and €251,320 for those assumed items combined, not a quoted import bill.
Source: Normattiva – import VAT calculation, updated 14 Mar 1997ADM Circular 11/2026 states that the maximum private-yacht temporary-admission period is 18 months from entry into the Union under Delegated Regulation (EU) 2015/2446, Article 217.
Source: ADM – temporary admission Circular 11/2026, updated 15 May 2026Section 4
Plan evidence of departure as carefully as evidence of arrival. The customs circular explains discharge of private temporary admission when the yacht leaves Union territorial waters and identifies evidence that can demonstrate the movement. An intention to leave is not a record of having left. As a practical recommendation, preserve the relevant movement data and supporting documents together. Ask the customs office to review uncertain evidence before relying on a later re-entry to support the yacht's customs history.
A yard booking is not enough to describe the customs treatment of repair work. The circular distinguishes ordinary maintenance that preserves the boat's intended use from work outside that scope. Give the representative an accurate description of the proposed work before it starts. Ask the yard which procedure it will use and who will hold it. Keep that answer with the work order. These recommendations help distinguish a maintenance job from a separate customs procedure without inventing a universal refit rule.
The identity of the procedure holder also matters when work takes place under a different arrangement. The circular gives a specific example involving the owner and a yard, with different holders and purposes. Do not turn that example into a promise that every repair pauses the private-admission clock. It also explains a private arrival where a skipper acts for an absent owner who joins later. Discuss the actual owner, user and skipper arrangement rather than assuming the person steering automatically holds the procedure.
Broker tip: Before authorising yard work, ask the yard and customs representative to confirm the procedure, holder and treatment of elapsed time in writing. Keep that explanation with the invoice and the yacht's movement records. Our guide on what safety equipment a boat must carry in Italy covers a related point.
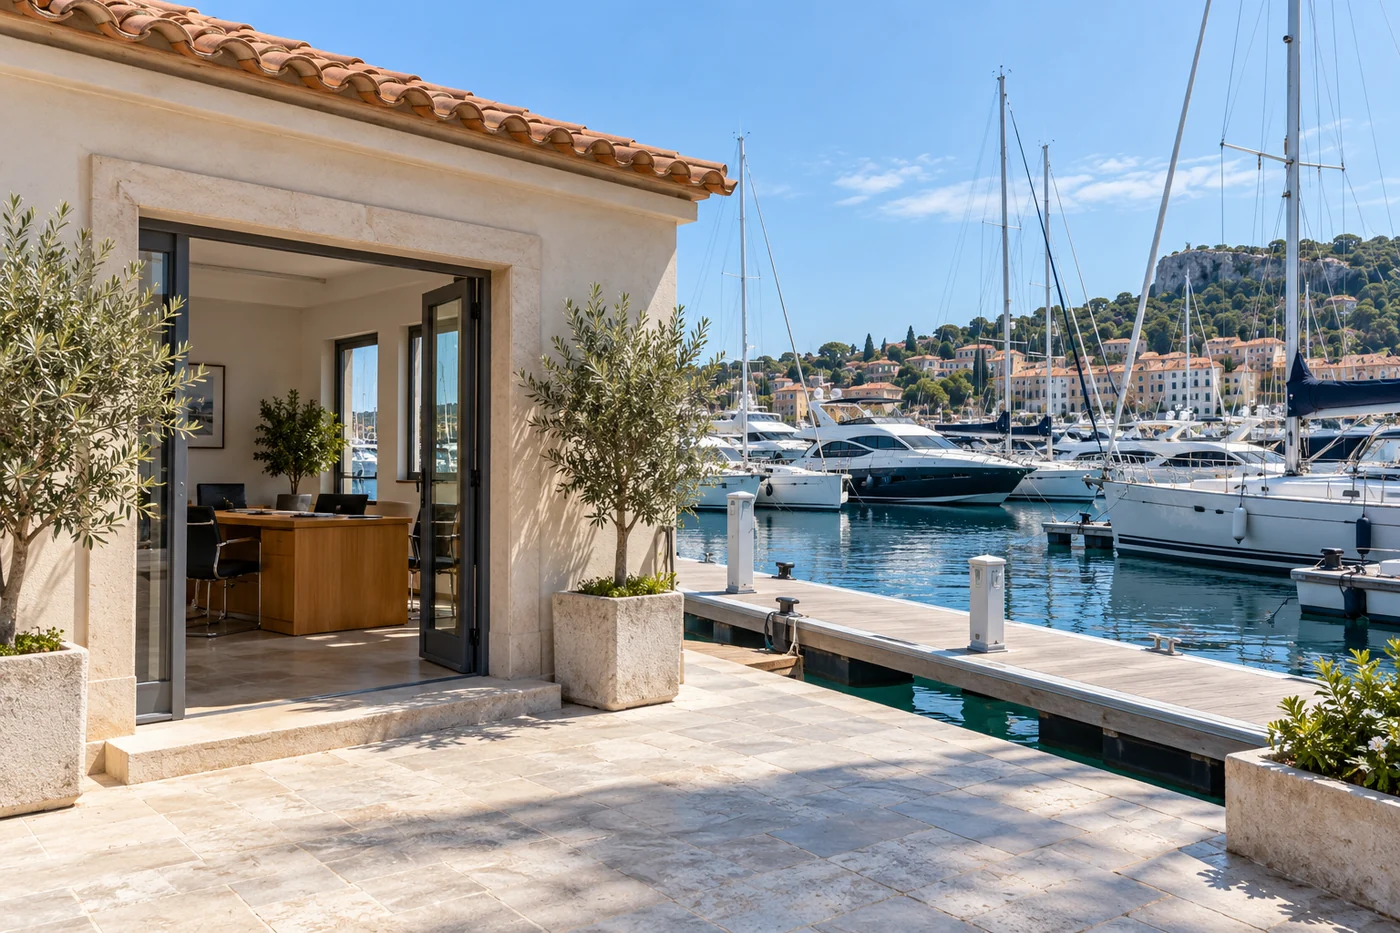
Boat registration at a marina office.
Departures and repairs
Practical support
Peter Mattey is a yacht broker at European Yacht Brokers with a BA in Law. He is not an Italian lawyer: for Italian law and tax we refer you to a locally qualified adviser. What we can do is help you plan the purchase, put the right questions to the seller and spot gaps in the paperwork before you commit.
If you are buying or selling a boat in Italy, tell us the type of boat, your budget and the area through the enquiry form on this page and a broker will reply. For anything this guide does not cover, email us at info@europeanyachtbrokers.com for the latest information.

Written by
Peter Mattey
Yacht Broker, European Yacht Brokers
BA (Law). Expert in marine law

The handover of a boat at the dock.
Your questions
No; permanent release for free circulation and qualifying private temporary admission are different customs routes. The former concerns non-Union goods intended for the Union market or private use, while the latter concerns non-Union goods intended for re-export under specified conditions. Ask a customs representative to assess the intended use, ownership and establishment before arranging delivery. A foreign flag alone does not settle the route. (EUR-Lex – Union Customs Code)
No; the private-yacht conditions also concern establishment of the registered person or owner and the user. The Italian customs circular explains those requirements together, rather than treating the flag as conclusive. Give the adviser the ownership and proposed-use arrangements before relying on the temporary route. This guide does not establish an exception for a Union-established user or a commercial charter. (ADM – temporary admission Circular 11/2026)
Keep evidence of entry into the Union, including an earlier member-state arrival before Italy. Under the simplified private-entry method, the circular places the burden of proving entry or a relevant subsequent exit on the procedure holder. It describes optional arrival-attestation routes as well as the use of documentary or other evidence. Assemble a coherent movement history for the customs representative to review. (ADM – temporary admission Circular 11/2026)
No; the statutory import base includes the customs value and specified additions. Customs charges other than VAT and relevant forwarding costs also enter the calculation described in the Italian VAT rule. Ask for those items to be shown separately, with the actual customs valuation and tax treatment for your transaction. The guide's assumed arithmetic is not a quotation for a real import. (Normattiva – import VAT calculation)
No automatic pause for every yard visit is established here. The customs circular distinguishes ordinary repairs from a specific inward-processing arrangement with different procedure holders and purposes. In that example, only the owner's temporary-admission periods count towards its limit. Ask the yard and customs representative to identify the actual procedure and holder before work begins, then preserve their explanation with the movement records. (ADM – temporary admission Circular 11/2026)
This guide does not set an import duty rate, agent fee or clearance time, because they depend on the boat and the customs assessment. The VAT arithmetic in this guide uses assumed amounts only. Email us at info@europeanyachtbrokers.com for the latest information, and ask a customs representative for a written calculation.
Ready when you are
SANLORENZO SX88 Built by Sanlorenzo in 2018, LADY LARISA combines contemporary Italian design with versatile living spaces and a seamless connection to the water. Exterior
RIVA FOLGORE MAYAR represents an exceptional opportunity to acquire one of the newest yachts in her class, combining iconic Italian styling with impressive performance and
We are delighted to introduce an exceptional market opportunity: the outstanding Pershing 8X, offered at an asking price of €4,690,000 + VAT. This superb 2024
Check it yourself
Regulation (EU) No 952/2013 establishing the Union Customs Code: declarations, documents, release for free circulation and temporary admission.
Italian customs guidance on private yacht entry, residence conditions, evidence, discharge and repairs.
Presidential Decree 633/1972, Article 69: import VAT taxable base.
Presidential Decree 633/1972, Article 16: ordinary VAT rate.
Keep reading
More guides for sellers and buyers: yacht brokers Italy.
More guides for sellers and buyers: yacht brokers Italy.
More guides for sellers and buyers: yacht brokers Italy.
Similar guides

More guides for sellers and buyers: yacht brokers Italy.
More guides for sellers and buyers: yacht brokers Italy.
More guides for sellers and buyers: yacht brokers Italy.
Talk to European Yacht Brokers
Looking for a boat in Italy? Tell us what you need
Tell us the type of boat, budget and area and a broker will reply.
More guides for sellers and buyers: yacht brokers Italy.
More guides for sellers and buyers: yacht brokers Italy.